Overview
Thank you for your interest in BBQ Quant Seminar. Event registration is closed at this time. If you have any questions email us at quantseminar@bloomberg.net
Please join us for May’s installment of the Bloomberg Quant (BBQ) Seminar Series – in-person in New York City. We look forward to seeing you at Bloomberg’s office once again.
In this special event chaired by Bruno Dupire, Nobel Prize winner Robert Engle will present the keynote, “Climate Financial Risk: Portfolios & Stress Tests,” followed by “lightning talks” of 5 minutes each in quick succession. All presentations will be done live on stage.
Because of COVID regulations, seating is limited and no walk-ins will be allowed. Please register early to secure your seat.
Agenda
- 5:00 pm
Check-in:
Proof of COVID vaccination (paper vaccine card or photo of your card, or an authorized state-based mobile app [e.g., NY Excelsior Pass]) is required for entry.
- 5:30 pm
Keynote: Robert Engle, 2003 Nobel Prize in Economics, Professor Emeritus of Finance, New York University
Climate Financial Risk: Portfolios & Stress Tests
How should investors use ESG to form portfolios? Several optimality criteria will be discussed. Both statistical and fundamental analysis of climate hedge portfolios will be presented. A Climate Efficient Factor Mimicking Portfolio will be defined as a portfolio of publicly available ESG portfolios. Its performance in the pandemic and more recently is examined and illustrated on VLAB. These climate hedge portfolios are then used to assess the climate sensitivity of banks by using the Dynamic Conditional Beta statistical procedure to get a climate beta. The presentation will illustrate the findings on financial stability with respect to climate risk. Capital adequacy with respect to climate scenarios will be defined as CRISK and Marginal CRISK and their chief determinants and robustness will be examined.
- 6:30 pm
Lightning talks
- Agnes Tourin | New York University
Robust approximations of trading strategies - Konstantin Soukhovetski | The Juilliard School
The science of narrative musicianship - Nelson Vadori | JPMorgan Chase
Calibration of derivative pricing models with reinforcement learning - Roza Galeeva | New York University
Deriving better derivatives
- Agnes Tourin | New York University
- 7:00 pm
Reception
Keynote Speaker
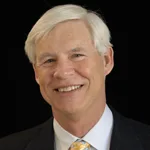
Robert Engle
Robert Engle, Professor Emeritus of Finance at New York University Stern School of Business, was awarded the 2003 Nobel Prize in Economics for his research on the concept of autoregressive conditional heteroskedasticity (ARCH). He developed this method for statistical modeling of time-varying volatility and demonstrated that these techniques accurately capture the properties of many time series. Professor Engle shared the prize with Clive W. J. Granger of UCSD. Professor Engle is the Co-Director of the Volatility and Risk Institute at NYU Stern. In this role he has developed research tools to track risks in the global economy and make these publicly available on the V-LAB website.
Bruno Dupire
Bruno Dupire is the Global Head of Quantitative Research, CTO Office at Bloomberg, which he joined in 2004. Prior to this assignment in New York, he has headed the Derivatives Research teams at Société Générale, Paribas Capital Markets and Nikko Financial Products where he was a Managing Director. He is best known for having pioneered the widely used Local Volatility model (simplest extension of the Black-Scholes-Merton model to fit all option prices) in 1993 and the Functional Itô Calculus (framework for path dependency) in 2009. He is a Fellow and Adjunct Professor at NYU and he is in the Risk magazine “Hall of Fame”. He is the recipient of the 2006 “Cutting edge research” award of Wilmott Magazine and of the Risk Magazine “Lifetime Achievement” award for 2008. He was also selected as the recipient of the 2025 Financial Engineer of the Year Award by the International Association for Quantitative Finance (IAQF) . He runs and organizes the Bloomberg Quant (BBQ) Seminar, the largest monthly event of this kind.
When & Where
Tuesday, May 24, 2022
5:00 pm – 8:00 pm EDT
Bloomberg L.P.
731 Lexington Avenue
7E MPR Room
New York, NY 10165