Join us for an in-depth discussion with leading industry experts as we examine the macroeconomic and market forces shaping volatility in 2026.
This session will explore:
• The key macro drivers behind today’s heightened market volatility
• The evolving relationship between oil, rates, and inflation
• Shifting expectations surrounding U.S. Federal Reserve policy
• How volatility is manifesting across asset classes
• Emerging opportunities in volatility markets and structured products
Whether you are managing risk, generating alpha, or structuring hedges, this discussion will provide timely insights into volatility as both a challenge — and an opportunity.
Spots are limited, RSVP now.
Speakers
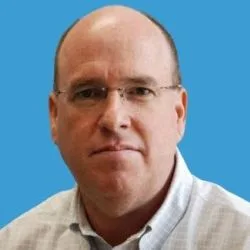
David Dredge
David Dredge is CIO, CEO and a Director of Convex Strategies Pte Ltd. Mr Dredge fulfilled these same roles while managing the Fund under City Financial Investment Company Pte Ltd. Prior to joining City Financial Investment Company Pte Ltd, Mr. Dredge worked as Co-Chief Investment Officer at Fortress Investment Group LLC. Prior to joining Fortress in 2011, Mr. Dredge was a Managing Director and Portfolio Manager at Artradis Fund Management in Singapore, where he was responsible for the non-equity aspects of their volatility based portfolio.
Previously, Mr. Dredge built Asian and Global EM businesses for RBS/ABN AMRO Group and Bankers Trust. Prior to that he performed various trading roles for Bank of America in San Francisco, London, Singapore, Jakarta, Tokyo and Hong Kong. Mr. Dredge is a main committee member of the Singapore Foreign Exchange Markets Committee (SFEMC).
Mr. Dredge graduated from University of Utah with a degree in Finance and completed an MBA at the University of California, Berkeley.
Stéphane Martin
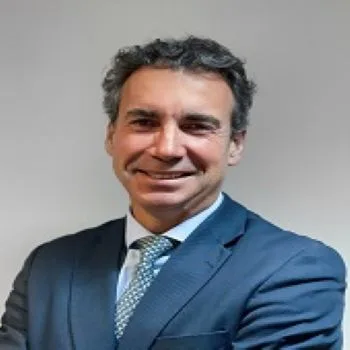
Diego Parrilla
Diego Parrilla, Chief Investment Officer at Quadriga Asset Managers in Madrid, where manages the volatility, tail risk, and protected equity mandates.
Diego has 27+ years of investment and senior leadership experience in London, New York, and Singapore across industry leaders JP Morgan, Goldman Sachs, Merrill Lynch, BlueCrest Capital, Dymon Asia, 36 South Capital. Diego is visiting lecturer at Imperial College Business School in London and co-author with Daniel Lacalle of “The Energy World is Flat” (Wiley, 2014), published in English, Spanish and Chinese, and “The Anti-Bubbles” (BEP, 2017), selective contributor to the Financial Times (published two Insight Columns), Wall Street Journal, CNBC, CNN, Bloomberg TV, Real Vision TV, Hedgeye, MacroVoices, amongst others. Diego holds a MSc Mineral Economics from the Colorado School of Mines in Golden, MSc Petroleum Economics and Management from the French Institute of Petroleum in Paris, and MSc Mining and Petroleum Engineering from the Polytechnic University of Madrid, and JP Morgan Global Markets Training program in NYC in 1998.
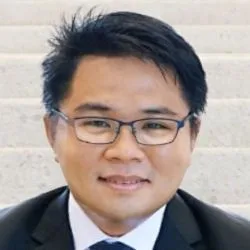
Wilson Er
Wilson Er is a derivatives and volatility-focused portfolio manager with deep expertise in tail risk strategies and systematic multi-strategy portfolio construction. At Vulpes Investment Management, Wilson leads the firm’s Tail Risk initiative , designing and managing option-based overlays that provide convex protection during periods of market dislocation. His work is grounded in over a decade of experience across structured products, proprietary trading, and hedge fund operations.
Before joining Vulpes, Wilson held senior roles proprietary trading desks, Macro hedge-fund, and multi family offices, where he developed and executed volatility strategies across equities, FX, and credit markets. He has built algorithmic frameworks for trading index options, managing complex multi-leg structures.
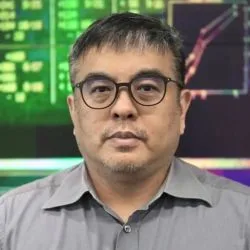
John Lagman
John Lagman is an APAC FX & FX Derivatives Market & Product Specialist for specializing in FX Derivatives. He joined Bloomberg at the end of June 2014, and works with the Sales teams to provide solutions to address the complex needs of the clients. In particular he builds Derivative & Systematics Signals, Dashboard and backtesters for Macro Hedge Funds in Hk and SG. John has 20+ years of experience as an FX Options Trader/Manager based in Singapore & the US. Previously, he also worked for 2+ years on the buyside as a Macro Quant Researcher & Execution Trader.